
Drive Your Business Forward with the Right Dealership Insurance
Why Auto Dealerships Need More Than Just Standard Business Insurance
{alt=”Exterior view of a modern auto dealership lot with multiple vehicles on display, representing the need for specialized insurance coverage.” title=”Auto Dealership Insurance Protection” caption=”Comprehensive insurance solutions for modern auto dealerships.” source=”PTL Insurance Associates, Inc.”}
Auto dealership insurance is a specialized type of business insurance designed to protect dealerships from the unique risks that come with selling, leasing, servicing, and maintaining vehicles. Unlike standard commercial insurance, it provides comprehensive coverage for vehicle inventory, customer vehicles in your care, test drive incidents, and garage operations liability.
Key coverages typically include:
- Garage Liability Insurance – Protects against third-party bodily injury and property damage claims during dealership operations
- Dealer’s Open Lot (DOL) Coverage – Physical damage protection for your new and used vehicle inventory against theft, vandalism, weather, and collision
- Garage Keepers Insurance – Covers damage to customer vehicles while they’re in your care, custody, or control for service or repair
- Optional Coverages – Cyber liability, employment practices liability, pollution liability, and business interruption insurance
Running an auto dealership involves risks most businesses don’t face: high-value inventory exposed to theft and weather, test drives on public roads, liability for customer vehicles in your service bay, and the potential for costly slip-and-fall lawsuits. With the rise of electric vehicles, advanced driver-assistance systems, and digital retailing, these risks have become even more complex. Standard commercial policies are not equipped to handle these specialized exposures.
This is why auto dealership insurance is essential. It’s more than an expense; it’s a financial safety net that protects you from the unexpected. Whether you run a franchised new car dealership, an independent used car lot, or a powersports dealership, the right coverage can be the difference between a minor setback and a business-ending crisis.
I’m Niki Perez, and at PTL Insurance Associates, I’ve worked alongside my husband Erik for years helping Miami-area dealerships steer the complex world of auto dealership insurance to find comprehensive coverage at competitive rates. Let’s break down what you need to protect your business and why specialized coverage is more important than ever.
Simple guide to auto dealership insurance terms:
What is Auto Dealership Insurance and Why is it Crucial?
Auto dealerships face a unique combination of risks, from test drives and service operations to high-value inventory and customer safety. Standard business insurance is not enough to cover these specific exposures.
The infographic below provides a quick overview of these risks.
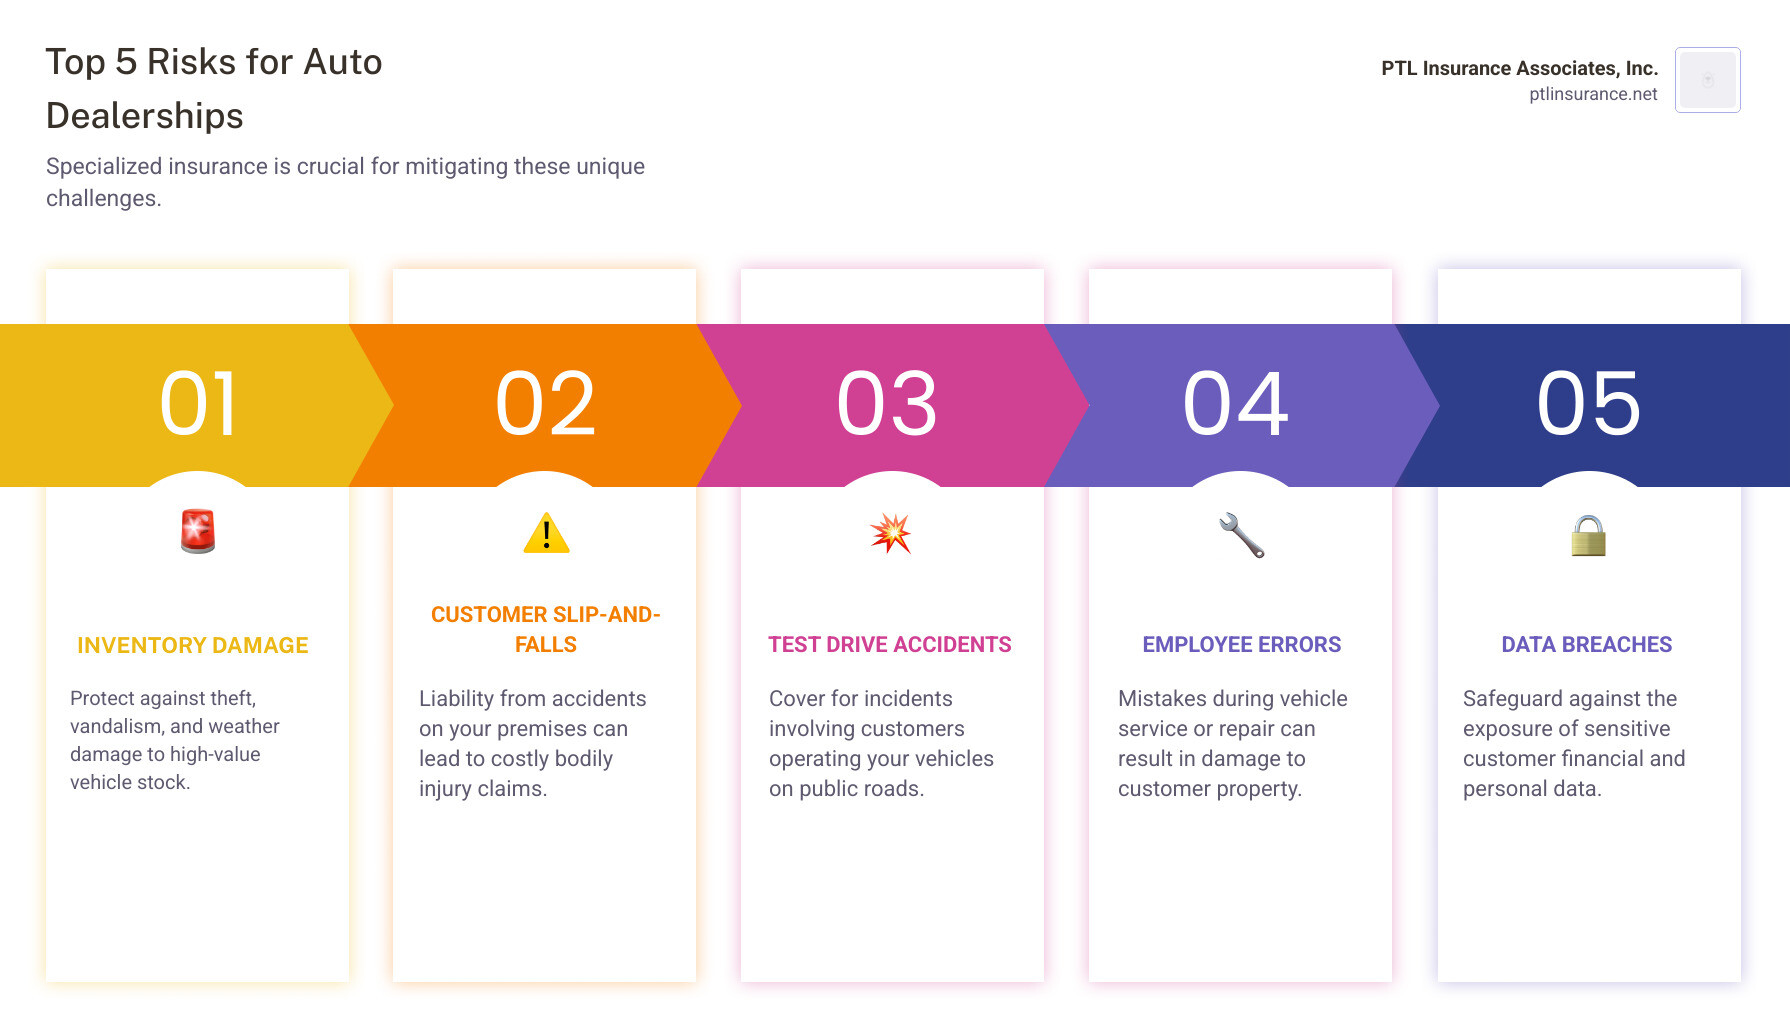
{alt=”Infographic summarizing the top five risks for auto dealerships, including inventory damage, customer injuries, test drive liability, service errors, and cyber threats.” title=”Top 5 Risks for Auto Dealerships” caption=”Visualizing common risks that auto dealership insurance addresses to help owners quickly grasp their exposure.” source=”PTL Insurance Associates, Inc.”}
The Unique Risk Landscape of an Auto Dealership
Operating an auto dealership in Miami, Florida, involves navigating a dynamic and challenging environment. The constant flow of customers, employees, and vehicles creates a high potential for incidents. Key risks include:
- Constant foot traffic: The high volume of people on your property increases the risk of slip-and-fall accidents and other third-party injuries, which are covered by garage liability insurance.
- Unfamiliar vehicle operation: Customers test-driving vehicles they don’t own can lead to accidents. A specialized policy is needed to cover the vehicle, driver, and any third parties involved.
- Maintenance and repair exposures: Your service center is responsible for customer vehicles. Any damage or mistakes during repairs can result in significant liability claims.
- Property and inventory protection: Your vehicle inventory is a major asset exposed to theft, vandalism, and severe weather like the hurricanes and floods common in Florida.
- Liability from sales and service: Beyond physical damage, dealerships face liability from sales transactions, including errors in paperwork and titling. Adhering to regulations from entities like the Florida Highway Safety and Motor Vehicles (FLHSMV) is critical. Additionally, pollution from service operations can lead to costly clean-up and lawsuits.
These exposures demonstrate why a generic business policy is inadequate and specialized coverage is necessary.
How Specialized Insurance Protects Your Bottom Line
Auto dealership insurance is a strategic investment in your business’s survival and success. It provides a robust financial safety net against numerous potential losses.
- Financial safety net: It acts as a buffer against the high costs of accidents, theft, property damage, and lawsuits. A single major incident could otherwise be financially devastating.
- Protection against lawsuits: In today’s litigious environment, a test drive accident or service error can lead to expensive legal battles. Specialized insurance covers defense costs and settlements.
- Ensuring operational stability: If a hurricane damages your lot, business interruption coverage can replace lost income during the closure, helping you recover faster.
- Safeguarding assets: The right policy protects your most valuable assets—your vehicle inventory, buildings, and equipment—from physical damage and theft.
- Peace of mind: Comprehensive coverage allows you to focus on growing your business, knowing you are protected from unforeseen events.
Core Coverages: The Non-Negotiable Protections
Every auto dealership needs a foundation of non-negotiable coverages to protect against the most common and devastating risks.
Garage Liability Insurance: Your First Line of Defense
Garage Liability is the cornerstone of a dealership’s policy, extending general liability to cover the unique risks of garage operations. It protects your business from claims of bodily injury or property damage to third parties arising from your premises, products, and operations.
Key protections include:
- Premises Liability: Covers incidents like a customer slipping and falling in your showroom or service center.
- Operations Liability: Applies to damage or injury caused during business operations, such as an accident during a test drive.
- Products Liability: Protects against claims arising from the vehicles you sell or the work you perform.
- Legal Defense Costs: Covers legal fees to defend your business against a claim, even if it’s baseless.
Dealer’s Open Lot (DOL) Coverage: Protecting Your Biggest Asset
Your vehicle inventory is your largest asset, and it’s constantly exposed. Dealer’s Open Lot (DOL) coverage provides physical damage protection for your new and used vehicles held for sale.
DOL typically covers:
- Collision: Damage from on-lot accidents.
- Theft and Vandalism: Protects against stolen vehicles or malicious damage.
- Weather Damage: Crucial for Florida dealers, this covers losses from hail, floods, and hurricanes.
Without robust DOL coverage, a single weather event or large-scale theft could severely damage your dealership’s financial stability.
Garage Keepers Insurance: Covering Customer Vehicles
If your dealership has a service department, Garage Keepers insurance is essential. It covers damage to a customer’s vehicle while it is in your care, custody, or control for service, repair, or storage.
This coverage applies to:
- Damage During Service: Protects against accidents in the service bay, like a mechanic denting a car or a lift malfunction.
- Theft or Fire: Covers a customer’s vehicle if it’s stolen from your property or damaged in a fire.
This protection is vital for maintaining customer trust and avoiding out-of-pocket costs for damage to vehicles you don’t own.
Expanding Your Shield: Optional Coverages and Key Differences
Common Optional Coverages to Consider
While core coverages are essential, different dealerships have unique risks that require additional protection. We work with our Miami clients to tailor policies with optional coverages like these:
- Cyber Liability Insurance: Protects against data breaches, which are a major threat given the sensitive customer financial data dealerships handle. It covers costs for data recovery, customer notifications, and regulatory fines.
- Employment Practices Liability (EPLI): Defends against claims from employees regarding wrongful termination, discrimination, or harassment.
- Errors & Omissions (E&O): Also known as professional liability, this covers claims of negligence in services like vehicle titling or financing paperwork.
- Pollution Liability: Crucial for service departments, this covers clean-up costs and lawsuits resulting from spills of waste oil, solvents, or other pollutants.
- Business Interruption: Replaces lost income and covers operating expenses if your dealership must temporarily close due to a covered event like a fire or hurricane.
How is this different from standard commercial auto insurance?
It’s a critical distinction. While both involve vehicles, auto dealership insurance is fundamentally different from a standard commercial auto policy. The latter is designed for businesses that own and operate vehicles for their own use (like a contractor’s truck), not for businesses that sell, service, and hold an inventory of vehicles.
Here’s a simple breakdown of the key differences:
| Feature | Auto Dealership Insurance | Standard Commercial Auto |
|---|---|---|
| Primary Purpose | Covers risks of selling, servicing, and storing vehicles. | Covers vehicles used for business operations (e.g., transport, service calls). |
| Inventory Coverage | Yes (Dealer’s Open Lot) – Protects vehicles for sale from theft, weather, etc. | No – Does not cover inventory held for sale. |
| Customer Vehicles | Yes (Garage Keepers) – Covers customer cars in your care for service/repair. | No – Does not cover non-owned vehicles in your care. |
| Test Drives | Yes (Garage Liability) – Covers liability during customer test drives. | Limited or no coverage for this specific risk. |
| Scope | A comprehensive package including liability for premises, operations, and products. | Primarily focused on liability and physical damage for owned business vehicles. |