


Vacation Rental Insurance Florida: Essential 2025 Protection
Why Florida Vacation Rental Owners Need Specialized Insurance Protection
Vacation rental insurance florida is not just recommended—it’s essential for property owners who rent their homes through platforms like Airbnb and VRBO. As the image above illustrates, a Florida vacation rental is a significant investment, but standard homeowners policies contain business activity exclusions that can leave you completely unprotected when renting to guests.
Quick Answer for Florida Vacation Rental Insurance:
- Standard homeowners insurance – Denies claims for rental activity due to business exclusions
- Landlord insurance – Designed for long-term tenants, not short-term guests
- Vacation rental insurance – Covers all three uses: owner stays, guest rentals, and vacancy periods
- Key coverage needed – Property damage, liability protection, and lost rental income
- Florida-specific risks – Hurricanes, guest amenities liability, and local regulations
Florida’s booming vacation rental market offers incredible income opportunities, but it also creates unique risks that most property owners don’t fully understand. With over 65 significant disasters declared in Florida since 1950 and the state’s complex patchwork of local rental regulations, the stakes couldn’t be higher.
The problem is simple: most vacation rental owners carry either homeowners or landlord insurance, both of which have significant coverage gaps when it comes to short-term rentals. These policies weren’t designed to handle the reality of paying guests using your property for business purposes.
As Niki Perez from PTL Insurance Associates, Inc., I’ve helped countless Florida property owners steer the complexities of vacation rental insurance florida after seeing how standard policies fail to protect rental investments. My experience in real estate management services has shown me exactly where coverage gaps create devastating financial risks for owners.
Why Standard Homeowners Insurance Isn’t Enough for Your Florida Rental
Here’s the harsh reality: your standard homeowners insurance will likely deny your claim the moment they find you’ve been renting out your property. It’s not personal—it’s business. And unfortunately, your rental activity is exactly the kind of business that makes insurance companies nervous.
The problem starts with something called a business activity exclusion. Your homeowners policy was written with the assumption that you and your family would be the only ones living there. The moment you start accepting payment from guests, you’ve crossed into commercial territory. Insurance companies see this as a completely different risk profile, and they’re not wrong.
Commercial use creates commercial risks. When you have a steady stream of unfamiliar guests coming and going, using your amenities, and treating your property like a hotel, the chances of something going wrong multiply dramatically. Your insurance company knows this, which is why they specifically exclude coverage for rental activities.
Now, you might be thinking, “What about landlord insurance?” While it’s definitely better than homeowners insurance, landlord policies are designed for long-term tenants, not short-term guests. There’s a huge difference between someone who signs a year-long lease and treats your property like their home, versus guests who might stay for just a weekend and see your place as their vacation playground.
The infographic below clearly illustrates the coverage gaps between standard policies and a dedicated vacation rental policy.
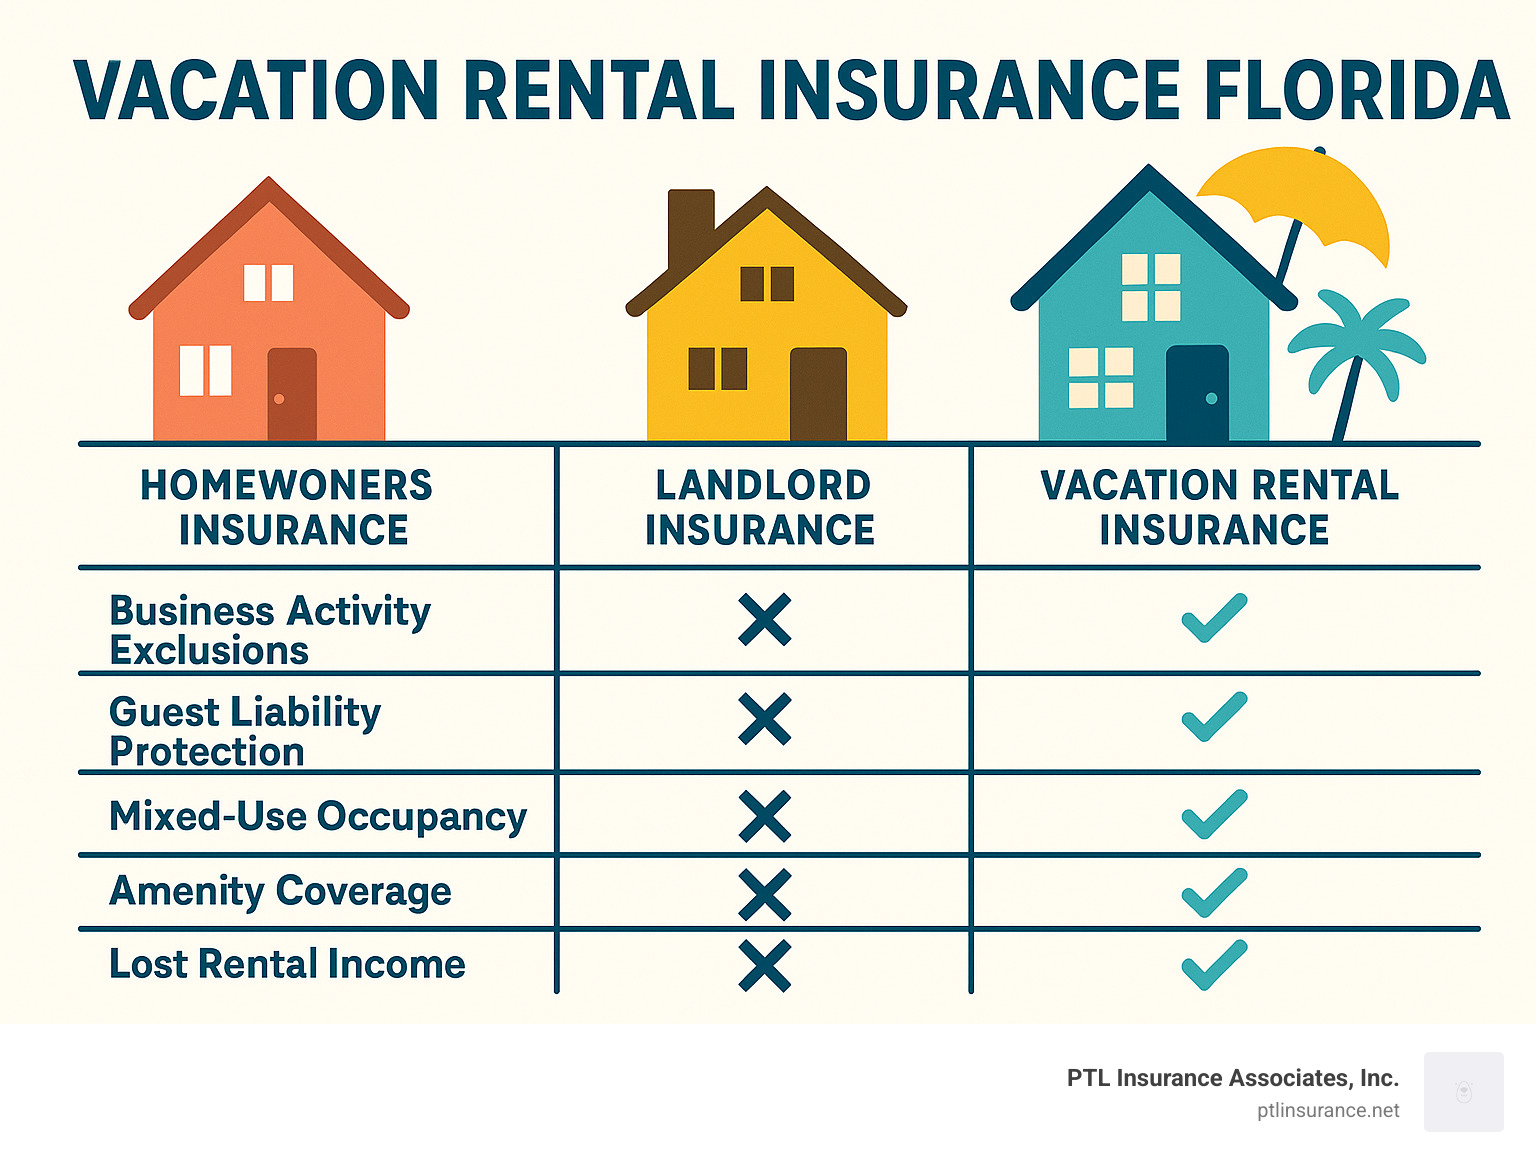
The insufficiency of riders and endorsements is another common trap. Some agents might suggest adding a “rental endorsement” to your existing homeowners policy for “occasional” rentals. This sounds convenient, but it’s often inadequate protection. These endorsements typically provide limited coverage and can still result in claim denials if your rental activity is deemed too frequent or commercial in nature.
This is why we recommend replacing your existing policy entirely with a specialized vacation rental insurance florida policy, rather than trying to supplement it with add-ons. A dedicated vacation rental policy is built from the ground up to handle your unique situation. It understands that your property serves three distinct purposes: hosting paying guests, providing a place for your own vacations, and sitting vacant between bookings.
Avoiding double insurance is crucial too. You don’t want to pay for overlapping coverage that might conflict with each other when it’s time to file a claim. A comprehensive vacation rental policy eliminates the guesswork and ensures you’re properly protected no matter how your property is being used on any given day.
The bottom line? Don’t gamble with your investment. Standard homeowners and basic landlord policies simply weren’t designed for the realities of today’s vacation rental business.
Unique Risks for Florida Vacation Rental Owners
Florida, with its stunning beaches, theme parks, and vibrant cities, is a magnet for tourists, making it a prime location for vacation rentals. However, this popularity comes with a unique set of challenges and risks that demand specialized insurance protection.
Navigating Natural Disasters and Weather-Related Risks
One of the most significant risks for any property owner in Florida is the threat of natural disasters. Florida is known for its susceptibility to hurricanes, tropical storms, and associated perils like windstorms and flooding. Since 1950, Florida has experienced 65 significant declared disasters, making it one of the most disaster-prone states in the nation.
These events can cause extensive property damage, from structural integrity issues to roof damage, which has become increasingly common in recent decades. Beyond the physical damage, a severe weather event can lead to a substantial loss of business income if your property becomes uninhabitable for an extended period. While standard policies might offer some hurricane coverage, specialized vacation rental insurance florida is crucial because it can provide business revenue protection, ensuring you don’t lose income during the recovery period. As more insurers exit Florida or limit hurricane coverage, finding comprehensive protection custom to short-term rental risks is paramount.
For more information on supporting small businesses in Florida, including disaster preparedness, you can visit the Helpful information for Florida small businesses.
Managing Guest-Related Liabilities and Damages
The transient nature of short-term rentals introduces a distinct set of risks related to guests. Unlike long-term tenants, guests are constantly changing, and their actions can lead to unexpected damages or liabilities.
Guest-caused damage is a common concern. This can range from accidental spills and broken items to more severe intentional acts like vandalism or even theft of property. Specialized policies can cover damages caused by guests, including intentional acts, and even theft of items from your rental.
Florida vacation rentals often come with amenities like swimming pools, hot tubs, golf carts, bicycles, paddleboards, or kayaks. While these improve the guest experience, they also significantly increase your liability exposure. If a guest is injured while using one of these amenities, whether on or off your premises, you could face a substantial lawsuit. A comprehensive policy will include specific amenity liability coverage that extends beyond just the property itself. Some policies even offer liquor liability coverage, which is crucial if you permit guests to consume alcohol on your property or provide alcoholic beverages as part of the rental experience, as this is typically excluded from standard policies.
Understanding Legal and Occupancy Challenges for vacation rental insurance florida
Beyond physical risks, operating a vacation rental in Florida involves navigating a complex web of legal and regulatory considerations. Florida’s approach to short-term rental regulations is diverse, varying significantly by city and county. What might be permissible in Miami could be restricted in Orlando or Fort Lauderdale. It is crucial for owners to understand the local ordinances specific to their property’s location to ensure compliance and avoid potential fines or legal issues.
Another evolving challenge is the risk of squatters. With the rise of flexible work arrangements and mid-term stays, some guests might attempt to overstay their welcome and claim tenant rights, making eviction a lengthy and costly process. Specialized policies can offer “squatter protection,” covering legal expenses and lost income associated with removing an unauthorized occupant.
Compliance with local laws and regulations is not just about avoiding penalties; it also plays a role in your insurance coverage. Insurers may require proof of compliance with local short-term rental laws to provide or honor coverage. This reinforces the need for an insurance partner who understands Florida’s unique regulatory landscape.
For assistance with navigating the business landscape in Florida, you can consult the Florida Small Business Development Center.
Core Components of a Comprehensive Vacation Rental Insurance Florida Policy
When you’re running a vacation rental business in Florida, you need more than basic property protection. A comprehensive vacation rental insurance florida policy acts like a three-legged stool—remove any component and the whole thing becomes unstable. Let’s walk through each essential piece that keeps your investment secure.
Property and Asset Protection
Your vacation rental represents years of hard work and significant financial investment. The building coverage in a specialized policy goes far beyond what you’d find in a standard homeowners policy, protecting against Florida’s unique perils like hurricanes, windstorms, and flooding damage.
The real game-changer is replacement cost coverage versus actual cash value protection. With replacement cost, if your kitchen appliances are damaged by a guest or destroyed in a storm, you’ll receive enough money to buy brand-new replacements—not some depreciated amount that leaves you scrambling to cover the difference.
This protection extends to everything that makes your rental special: your carefully chosen furniture, high-thread-count linens, that expensive coffee machine guests love, and even your outdoor grilling equipment. Unlike standard policies that might exclude guest-caused damage, a proper vacation rental policy covers theft and damage caused by your paying guests.
Don’t forget about those special touches that set your property apart. Your pool equipment, hot tub, outdoor furniture, and recreational gear like bicycles or kayaks all need specific protection for amenities. These items face constant use from different guests and require coverage that understands this unique wear and tear.
Liability Coverage for Your Business
Here’s where things get serious. When you welcome strangers into your property, you’re taking on significant liability risks that can potentially wipe out your financial future. Commercial general liability coverage should start at a minimum of $1 million per occurrence—and honestly, in today’s lawsuit-happy world, higher limits often make sense.
Think about it: a guest slips by your pool and breaks their leg. They could sue for medical bills, lost wages, pain and suffering, and more. Without proper coverage, you’re personally on the hook for potentially hundreds of thousands of dollars.
But liability extends beyond just your property boundaries. Off-premises amenity liability covers situations where a guest gets injured using equipment you provided—like if they crash the bicycle you lent them or flip the kayak while exploring a nearby lake.
Pet and animal liability is another crucial component, especially since many successful rentals welcome furry family members. If a guest’s dog bites another guest or damages property, you need protection. Quality policies often provide this coverage without breed restrictions.
Even less obvious risks like libel and slander protection can save you from costly legal battles if a disgruntled guest makes false claims about you online or in reviews.
Protecting Your Revenue Stream
Your vacation rental isn’t just a property—it’s a business that generates income you likely depend on. When disaster strikes, the property damage is only part of your problem. The bigger issue? Loss of rental income while your property sits empty during repairs.
Business revenue protection compensates you for actual lost bookings when your property becomes uninhabitable due to a covered claim. The best policies offer this protection without arbitrary time limits, recognizing that major repairs—especially after hurricanes—can take months or even longer in Florida’s competitive construction market.
This coverage becomes even more valuable when you consider Florida’s hurricane season. If a storm damages your roof in August, you could miss out on lucrative fall and winter bookings while waiting for repairs. Quality vacation rental insurance florida policies understand this reality and provide comprehensive income replacement.
Modern policies also address unique challenges like bed bug and pest remediation costs. These little nightmares can shut down your rental for weeks while you deal with extermination and deep cleaning. The lost income during treatment, combined with the remediation costs, can easily reach thousands of dollars—expenses that standard policies simply don’t cover.
The peace of mind that comes from knowing your investment, your liability exposure, and your income stream are all properly protected? That’s priceless for any serious vacation rental owner.
Frequently Asked Questions about Florida Rental Insurance
Over my years helping Florida property owners at PTL Insurance Associates, Inc., I’ve noticed the same questions come up again and again. Whether you’re just starting your vacation rental journey or looking to upgrade your existing coverage, these are the concerns that keep owners up at night. Let me address the most common ones with straightforward answers.
Does vacation rental insurance cover me when I stay at my property?
This is hands down one of the most frequent questions I hear, and I love answering it because the response is so reassuring: absolutely yes!
A comprehensive vacation rental insurance florida policy is designed for mixed-use properties, covering periods of owner occupancy, guest stays, and vacancy without any restrictions. This ensures your property is protected no matter who is using it.
Think about it this way – your property serves three different purposes throughout the year. Sometimes you’re there enjoying your own little slice of paradise. Other times, paying guests are creating memories (and hopefully treating your place well!). And then there are those quiet periods when nobody’s there at all.
Unlike standard homeowners policies that assume you’re always there, or landlord policies that assume you never are, vacation rental insurance gets the reality of your situation. You’re running a business, but you also want to enjoy your investment. There’s no need to worry about coverage gaps when you decide to take a last-minute weekend at your own place.
What’s the difference between my property insurance and the travel insurance my guests buy?
I get this question a lot, and it’s completely understandable why there’s confusion. These are two entirely different types of protection that serve completely different purposes.
Your vacation rental insurance florida is property and casualty insurance that protects you, the owner, from financial loss related to your property, assets, and liability. Travel insurance is purchased by guests to protect their financial investment in their trip, covering things like trip cancellation, interruption, or medical emergencies during their travels.
Your insurance is all about protecting your investment and your business. It covers the building, the furnishings, your liability if someone gets hurt, and your lost income if something goes wrong. It’s designed to keep your rental business running smoothly.
Guest travel insurance, on the other hand, protects their vacation investment. If they get sick and can’t travel, if there’s a family emergency, or if their flight gets cancelled, their travel insurance helps cover those costs. It might also help with medical emergencies while they’re traveling or lost luggage situations.
Here’s the key point: their travel insurance doesn’t protect you at all. If a guest damages your property or gets injured in your pool, their travel insurance won’t help with your costs or liability. That’s exactly why you need your own robust coverage.
Can I get a policy if my rental property is owned by an LLC or Trust?
Absolutely! In fact, this is becoming more and more common, and for good reason.
Yes, because a vacation rental is a business, specialized insurance policies are designed to be written in the name of an individual, partnership, LLC, corporation, or trust, ensuring your business entity is properly protected.
Many savvy property owners choose to hold their rental properties under an LLC or trust for legal and financial protection. It’s actually a smart move that can provide an extra layer of protection for your personal assets. The good news is that specialized vacation rental policies are built to accommodate this business structure.
When you set up your policy, we can write it with your LLC, corporation, or trust as the named insured. This ensures that your business entity is properly recognized and protected by the insurance policy. Everything aligns perfectly – your legal structure, your financial setup, and your insurance coverage all work together.
The flexibility of these policies is really impressive. Whether you’re a solo owner, have a business partner, or have set up a more complex business structure, the right vacation rental insurance florida policy can be custom to fit your specific situation. It’s just one more reason why specialized coverage makes so much more sense than trying to make a standard homeowners policy work for your rental business.
Conclusion: Secure Your Investment with the Right Protection
Florida’s vacation rental market offers incredible opportunities to generate income while sharing your piece of paradise with travelers from around the world. But as we’ve finded throughout this guide, those golden opportunities come with some serious risks that most property owners don’t fully understand until it’s too late.
The reality is stark: standard homeowners and landlord policies simply weren’t designed for the modern vacation rental business. They leave you exposed to business activity exclusions, guest-related damages, and complex liability situations that can wipe out years of rental income in a single claim. Add Florida’s unique challenges—from hurricane season to local regulatory requirements—and you’re looking at a perfect storm of potential financial disaster.
This is where specialized vacation rental insurance florida becomes your financial lifeline. It’s not just another insurance policy; it’s a comprehensive business protection strategy that covers every angle of your rental operation. Your property and contents are protected with replacement cost coverage, your liability exposure is managed with robust commercial coverage, and your income stream stays secure even when disasters strike.
The peace of mind that comes with proper coverage is invaluable. When hurricane season arrives or when an unexpected guest incident occurs, you’ll sleep soundly knowing your investment is truly protected.
At PTL Insurance Associates, Inc., we’ve been helping Florida property owners steer these complex insurance waters for over 35 years. As an independent broker in Miami, we understand the unique challenges facing vacation rental owners across the state. Our personalized approach means we don’t just sell you a policy—we craft coverage solutions that fit your specific property, your business model, and your financial goals.
Your vacation rental represents a significant investment in your financial future. Don’t gamble with inadequate coverage when comprehensive protection is within reach. The cost of specialized insurance is minimal compared to the devastating losses you could face without it.

