


Condo Insurance Miami Florida: Top 5 Must-Know Tips 2024
Condo insurance miami florida is a critical consideration for every Miami resident who owns a condominium. As one of the Sunshine State’s most vibrant cities, Miami calls for practical measures to safeguard your home against various risks. Here’s what you need to know:
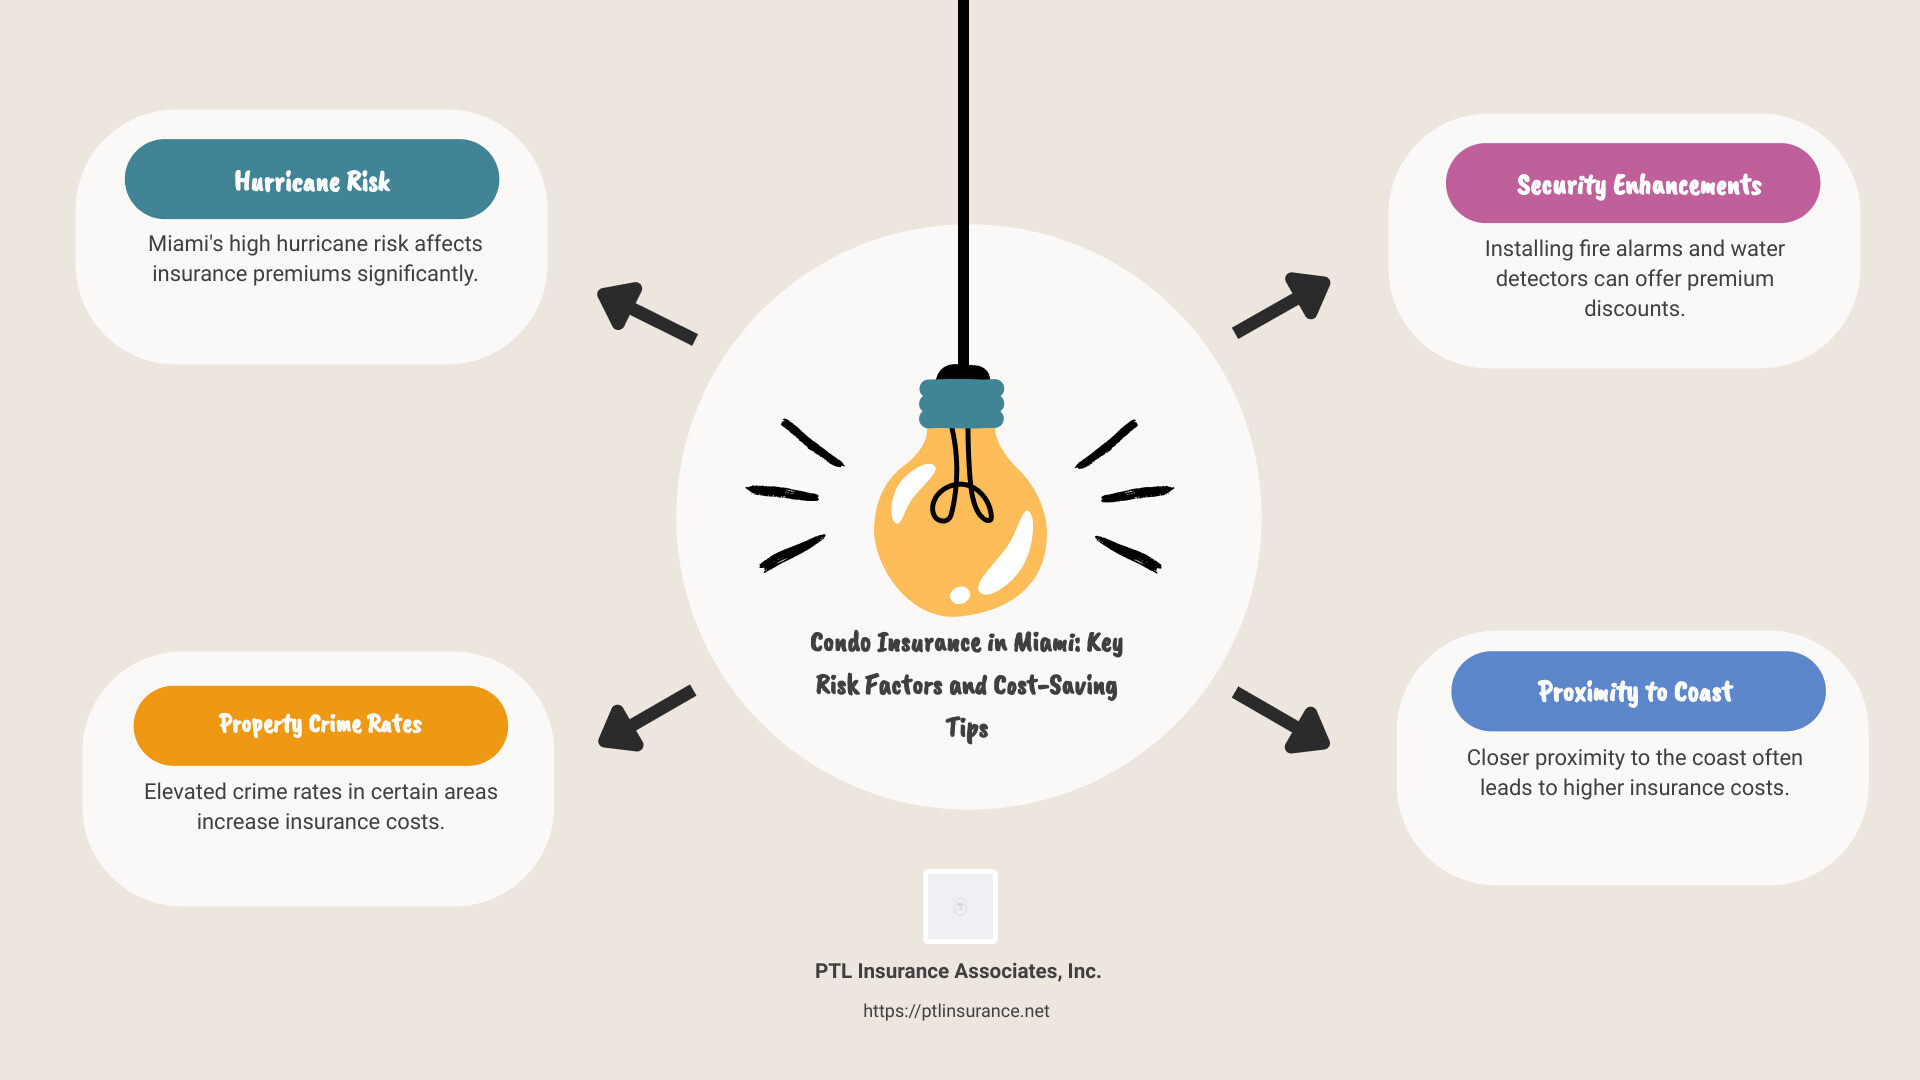
- Risk Factors in Miami:
- High hurricane risk impacts insurance costs.
Liftd property crime rates necessitate secure coverage.
Cost Considerations:
- Insurance rates vary; factors include the condo’s location and structure.
Premiums may be influenced by proximity to the coast and building age.
Mitigating Costs:
- Discounts available for security improvements, like fire alarms and water detectors.
PTL Insurance Associates, Inc., a dedicated provider in Miami, specializes in finding the right coverage to protect your investment. My name is Niki Perez, and with years of hands-on experience in condo insurance miami florida, I’m here to guide you through understanding and navigating your insurance options seamlessly.
Key terms for condo insurance miami florida:
– homeowners insurance miami condo
– how much is home insurance in miami
– miami home insurance companies
Understanding Condo Insurance in Miami
Condo insurance in Miami is essential for protecting your investment against the unique risks of the area. Here’s what you need to know about the costs, factors affecting rates, and whether it’s mandatory.
Average Cost of Condo Insurance in Miami
In Miami, condo insurance costs significantly more than the national average. The average annual cost is around $2,570, which breaks down to about $214 per month. This is more than double the U.S. average of $455 per year.
Factors Affecting Condo Insurance Rates
Several factors influence the cost of your condo insurance in Miami:
Hurricane Risk: Miami’s location makes it highly susceptible to hurricanes. This increased risk leads to higher insurance premiums to cover potential wind damage.
Property Crime: Miami has a property crime rate of 29 per 1,000 residents. This translates to a 1 in 39 chance of being a victim, which can drive up insurance costs.
Building Structure and Age: High-rise buildings or older structures might face higher premiums due to increased risk of damage or repair costs.
Proximity to the Coast: Condos closer to the coastline are more vulnerable to storm surges and flooding, impacting insurance rates.
Is Condo Insurance Mandatory in Florida?
While Florida law doesn’t mandate condo insurance for individual unit owners, it’s highly recommended. Most condo associations require owners to have an HO6 policy as part of their bylaws. This policy covers personal property, liability, and sometimes loss assessment.
Coverage Gaps: Although your condo association’s master policy covers common areas, it typically doesn’t include your personal belongings or liability inside your unit. This makes individual condo insurance crucial for comprehensive protection.
Understanding these aspects of condo insurance in Miami helps you make informed decisions about protecting your home. Stay tuned as we dig deeper into the types of coverage available in the next section.
Types of Condo Insurance Coverage
Condo insurance in Miami, Florida, is essential for safeguarding your investment. Understanding the different types of coverage available can help you make informed decisions.
HO6 Policy Explained
The HO6 policy is a standard condo insurance policy designed for individual unit owners. It covers several key areas:
Dwelling Coverage: This part of the policy protects the interior of your condo, including walls, floors, and ceilings, against damage from covered events like fire or vandalism. It’s crucial because the condo association’s policy usually only covers the building’s exterior and common areas.
Personal Property: This coverage protects your belongings, such as furniture, electronics, and clothing, against loss or damage. You can choose between actual cash value or replacement cost coverage. The latter may offer more comprehensive protection by covering the cost to replace items with new ones.
Liability Coverage: If someone is injured in your condo, this coverage helps protect you against legal claims and medical expenses. It’s a financial safeguard against accidents that could otherwise lead to costly lawsuits.
Loss Assessment: If your condo association imposes a fee for shared area damages or liability claims, loss assessment coverage can help cover your share of these costs. In Florida, policies must include at least $2,000 for loss assessment, but you might want to consider higher limits.
Additional Coverages
Given Miami’s unique risks, it’s wise to consider additional coverages:
Wind Mitigation: This coverage helps protect against wind damage from hurricanes. Installing features like storm shutters or reinforced roofs can reduce premiums and improve protection.
Fire Alarms and Water Leak Detectors: Installing these devices can not only protect your home but also qualify you for discounts on your insurance. They help detect and mitigate damage early, potentially saving you from costly repairs.
Flood Insurance: Standard condo insurance policies typically do not cover flooding. Given Miami’s vulnerability to storm surges, flood insurance is a critical add-on for comprehensive protection.
Catastrophic Ground Cover Collapse: Unique to Florida, this coverage protects against sudden ground collapses that render your condo uninhabitable. While rare, it’s a valuable safeguard given Florida’s geological conditions.
By understanding these coverage options, you can better protect your Miami condo from the area’s unique risks. Stay tuned as we explore how to save money on your condo insurance in the next section.
How to Save Money on Condo Insurance
Condo insurance can be pricey, especially in a high-risk area like Miami, Florida. But there are ways to save money while still getting the protection you need.
Discounts Available
Many insurance companies offer discounts that can significantly reduce your premium. Here are some common ones:
Wind Mitigation: Miami’s hurricane risk is high, so insurers often reward condo owners who install wind mitigation features like storm shutters or impact-resistant windows. These features can reduce potential damage, which means lower costs for insurers and savings for you.
Fire Alarms and Water Leak Detectors: Installing these safety devices can qualify you for discounts. They help prevent and minimize damage, making your condo less risky to insure.
Secured Community: Living in a gated or secured community can also lower your insurance rates. These communities typically have lower crime rates, which reduces the risk of theft or vandalism.
Tips for Reducing Premiums
Beyond taking advantage of discounts, there are other strategies to reduce your condo insurance costs:
Comparison Shopping: Don’t settle for the first quote you receive. Comparison shopping can help you find the best deal. Different insurers weigh risks differently, so rates can vary widely.
Bundling Policies: If you have other insurance needs, like auto or life insurance, consider bundling them with the same provider. Many companies offer discounts for multiple policies.
Increasing Deductibles: Opting for a higher deductible can lower your premiums. Just make sure you can afford the deductible in case of a claim.
By implementing these strategies, you can manage the cost of your condo insurance without sacrificing coverage. Stay informed and proactive to ensure you’re getting the best deal possible.
Frequently Asked Questions about Condo Insurance in Miami
What is the Average Cost for Condo Insurance in Florida?
The average cost of condo insurance in Florida is $1,130 per year. This is significantly higher than the national average of $455 per year. However, this average can vary greatly depending on where you live in Florida. For example, Miami’s average annual cost is $2,570, making it one of the most expensive cities for condo insurance in the state.

How Much is Insurance on a Condo in Miami Beach?
Condo insurance in Miami Beach tends to be on the higher end due to the area’s increased risk factors. Proximity to the coast, hurricane risk, and property crime rates all contribute to these costs. While exact prices can vary, you can expect to pay a premium similar to or slightly higher than the Miami average of $2,570 per year. Factors like your building’s structure and age, as well as any installed safety features, will also affect your specific rate.
Is it Mandatory to Have Condo Insurance in Florida?
While the state of Florida does not legally require condo owners to have insurance, it is highly recommended. Condo associations often mandate insurance coverage to protect both the unit and communal areas. These associations typically hold a master policy that covers common areas, but it won’t cover personal belongings or liability within your unit. Therefore, having a personal condo insurance policy can fill these coverage gaps and provide peace of mind.
Conclusion
In summary, condo insurance in Miami, Florida is not just a wise choice—it’s essential for protecting your investment. With Miami’s unique risks, such as hurricanes and higher property crime rates, having the right coverage can save you from significant financial loss. While the state doesn’t mandate it, most condo associations do, emphasizing its importance.
Custom coverage is key. Each condo and owner is different, and a one-size-fits-all policy won’t always provide the protection you need. At PTL Insurance Associates, Inc., we understand that. Our 35 years of experience in the Miami area have taught us the value of personalized service and custom insurance solutions. We work with you to find the right mix of coverage options, ensuring that your condo, belongings, and liability are all adequately protected.
If you’re looking for expert advice and a policy that fits your unique needs, we invite you to explore our home insurance services. Let us help you find peace of mind with a policy that’s just right for you.

